
 By
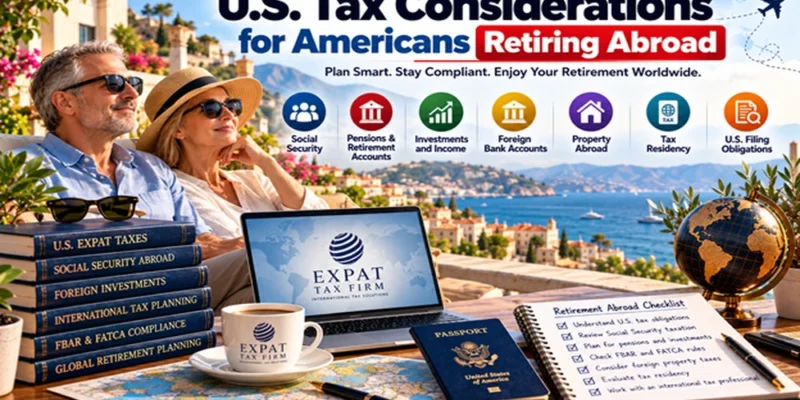
Retiring overseas can offer Americans an opportunity to experience a different lifestyle, lower living costs, or closer proximity to family and communities abroad. But moving into retirement in another country does not automatically end U.S. tax responsibilities. For U.S. citizens and resident aliens, worldwide income is generally subject to U.S. income tax, and living outside the United States does not by itself eliminate federal filing obligations.
For retirees, the tax picture can become more complex because income may come from several sources at once. Social Security, pensions, retirement accounts, investments, rental property, and foreign financial accounts can all require consideration. Understanding these issues before moving abroad can make retirement planning more organised and help avoid unexpected reporting problems.
Social Security Benefits
Social Security is often one of the most important income sources for retirees, but its tax treatment can vary.
The IRS explains that Social Security benefits received by U.S. citizens and resident aliens may be taxable depending on total income and filing status. Tax treaties can also affect how certain benefits are treated in particular countries.
An American retiree moving overseas should therefore consider both U.S. rules and the rules of the country where they intend to live. The fact that Social Security is a U.S. government benefit does not necessarily mean it will be treated identically for tax purposes in another country.
Before relocating, retirees may want to review how their destination country’s tax system treats Social Security and whether an applicable tax treaty contains provisions affecting the benefit.
Pensions and Retirement Accounts
Pensions and retirement accounts can introduce additional questions.
A retiree may receive income from a traditional IRA, 401(k), pension, annuity, or another retirement arrangement. The U.S. tax treatment can depend on the type of account and the nature of the distribution.
Foreign pensions can be particularly important to review because the country where the pension originates may have its own taxation rules, while the United States may also have reporting or tax considerations.
The IRS notes that U.S. taxpayers abroad generally remain subject to the same basic income tax rules that apply to taxpayers living in the United States.
This means moving overseas should generally be treated as a change in the taxpayer’s circumstances rather than an automatic end to U.S. tax obligations.
Investment Income
Retirement portfolios can generate dividends, interest, capital gains, and other investment income.
For an American living abroad, these sources remain relevant to the U.S. tax return because U.S. citizens and resident aliens generally must consider worldwide income.
Investments held in the United States may be relatively straightforward from a U.S. reporting perspective, but investments established after moving overseas can require closer examination. Certain foreign investment products can have complex U.S. tax treatment, so retirees should understand how a foreign investment will be treated before transferring significant savings into it.
Currency movements can also matter. Income and expenses received or paid in foreign currency generally need to be translated into U.S. dollars for U.S. tax reporting.
Foreign Bank Accounts
A retiree living abroad will often establish or maintain foreign bank accounts for everyday expenses, savings, investments, or pension payments.
Foreign accounts can create reporting obligations separate from the regular income tax return. The IRS states that an FBAR generally applies when the aggregate value of qualifying foreign financial accounts exceeds $10,000 at any time during the calendar year.
Some taxpayers may also have Form 8938 obligations when specified foreign financial assets exceed applicable thresholds. These requirements are separate from the basic requirement to report taxable income.
Keeping accurate records of account numbers, institutions, balances, interest, dividends, and other relevant information can make annual reporting considerably easier.
Owning Property Overseas
Buying a home overseas can also create tax questions.
A retiree might purchase a primary residence, holiday property, or rental property in the country where they live. The tax treatment can depend on how the property is used.
Rental income, for example, may need to be considered for U.S. tax purposes as well as under local law. A future sale could also create capital gains considerations.
The property may also affect local tax residency, inheritance planning, estate considerations, and other obligations. Consequently, purchasing foreign real estate is not simply a lifestyle decision; it can become part of a broader international tax picture.
Tax Residency in the Retirement Country
One of the most important issues to investigate before retiring abroad is local tax residency.
The country where a retiree spends most of their time may have its own residency rules based on factors such as days present, permanent home, economic connections, or other circumstances. These rules vary significantly between countries.
A person can therefore be a U.S. tax resident for federal purposes while also being considered tax resident somewhere else under local law. Tax treaties may provide rules for resolving certain residency conflicts, but the outcome depends on the specific treaty and individual facts.
Understanding local residency before moving can help retirees anticipate how their Social Security, pensions, investments, property, and other income may be treated.
Continuing U.S. Filing Obligations
Retiring abroad does not automatically remove the requirement to file a U.S. return.
The IRS states that U.S. citizens and resident aliens living overseas generally have the same income tax filing requirements as those living in the United States, with filing generally determined by factors including worldwide income, filing status, and age.
Additional information returns may apply depending on a retiree’s foreign accounts, foreign entities, trusts, or other assets.
For this reason, retirement planning should include a review of both income taxation and information reporting rather than focusing solely on the amount of tax ultimately owed.
How International Tax Planning Can Help
Professional international tax planning can help retirees organise their financial affairs before and after an overseas move. A planning review may examine expected retirement income, Social Security, pensions, investments, foreign bank accounts, property, tax residency, treaty considerations, and U.S. reporting requirements.
Expat Tax Firm publicly lists expat tax planning, expat tax returns, FBAR and foreign reporting, FATCA compliance, and retirement planning related services among its international tax offerings. Its current website identifies Mitchell Propster as founder and lists him as a CTC and Team Leader.
Retirees interested in learning more about Mitchell Propster’s professional background can also visit his LinkedIn profile.
Planning Before the Move
Retiring abroad involves more than selecting a destination and arranging accommodation. From a tax perspective, it can be useful to review the complete financial picture before relocating.
Social Security, pensions, investments, foreign accounts, property, local residency, and U.S. filing requirements can interact in ways that are not always obvious. Planning ahead can give retirees a clearer understanding of their obligations and help them maintain accurate records once they begin living overseas.
Most importantly, the tax consequences of retirement abroad depend on the individual’s circumstances and the laws of both countries involved.
Disclaimer: This article is intended for general educational purposes only and does not constitute tax, legal, financial, or retirement advice. International tax rules vary by country and individual circumstances. Taxpayers considering retirement abroad should consult the IRS, applicable tax authorities, and a qualified international tax professional about their specific situation.

Comments